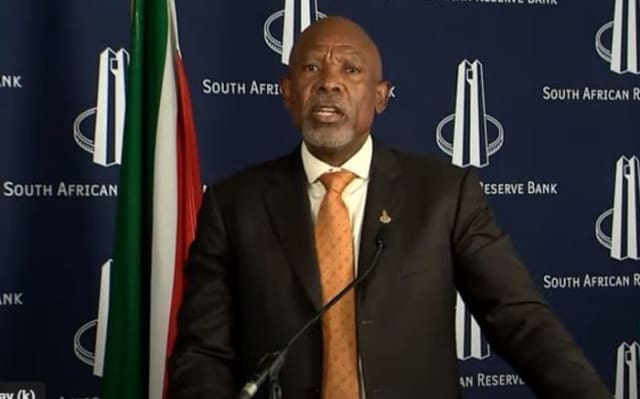
The South African Reserve Bank (SARB) has raised its benchmark repo rate by 25 basis points to 7.25%, effective from 25 September, in a unanimous decision by the Monetary Policy Committee (MPC). The move brings the prime lending rate to 10.75%.
Announcing the decision, Reserve Bank Governor Lesetja Kganyago said the global environment remains “challenging and uncertain,” citing the escalating Middle East conflict, interruptions to oil exports from Saudi Arabia due to fighting in Yemen, and the ongoing Russia-Ukraine war as key factors driving inflation higher.
“The global environment remains challenging and uncertain,” Kganyago said in the statement issued by the Monetary Policy Committee.
“These geopolitical events add up to a large, negative and persistent global supply shock, creating additional inflationary pressures.”
The decision comes despite South Africa’s headline inflation rate rising only marginally to 4.4% in August 2026, up from 4.3% in July, according to Statistics South Africa.
The figure came in below economist expectations of around 5.0%, largely due to lower petrol prices during the month. However, fuel costs have continued to climb in September, with petrol rising by R1.34 per litre and diesel by R3.15 per litre.
Kganyago noted that the central bank has raised its near-term inflation forecasts, mainly because of higher fuel prices.
“Headline inflation will likely be above 5% later this year and early next year, before slowing as the fuel shock recedes,” he said.
“We currently expect inflation to be back around 3% towards the end of 2027.”
Global Central Banks Tighten as Inflation Risks Mount
The SARB’s decision follows a wave of rate hikes by major central banks, including the European Central Bank, the Bank of Japan, and the United States Federal Reserve, which raised rates last week for the first time in three years.
“We have also seen longer-term interest rates moving higher recently, with various benchmarks reaching multi-decade highs,” Kganyago said.
“The main drivers of this include large fiscal deficits in major economies, as well as inflation risks, and heavy borrowing to fund infrastructure for Artificial Intelligence.”
The Governor acknowledged that world growth is holding up but warned that “shocks are multiplying and vulnerabilities are increasing.”
South African Economy Contracts in Second Quarter
Turning to domestic conditions, Kganyago noted that the economy contracted by 0.2% in the second quarter, confirming the MPC’s earlier warning of downside risks to growth. The central bank still projects an annual growth rate of 1.2% for 2026, with a rebound expected in the second half of the year.
“The global shocks are clearly hurting our economy,” Kganyago said.
“We continue to project growth of around 2% over the medium term. This is based on global conditions stabilising, and domestic reforms delivering a better business environment. Our assessment is that growth risks are skewed to the downside.”
Food Inflation at Lowest Since 2010, But Services Prices Remain Elevated
While fuel prices continue to pressure the inflation outlook, Kganyago highlighted more favourable developments in food and core goods inflation. Food inflation is at its lowest since 2010, reflecting strong harvests and a levelling off in meat prices following the foot-and-mouth disease outbreak.
“Import prices remain contained, with help from the rand, which has been notably resilient throughout the year,” Kganyago said.
However, services inflation remains elevated, with price hikes well above the 3% inflation target in many categories. “An important part of lowering services inflation is getting inflation expectations lower,” the Governor noted, adding that longer-run expectations remain around 4% rather than the 3% target.
MPC Considered Higher Global Rates and Inflation Expectations Scenarios
The MPC considered two alternative scenarios in its risk assessment. The first involved higher global interest rates, with major central banks raising rates by a full percentage point between this year and next. This scenario would cause rand depreciation, lifting inflation and prompting a tighter policy stance with rates about one hike above the baseline path.
The second scenario examined higher inflation expectations and wage increases, which also showed a tighter policy stance with between one and two hikes above the baseline peak.
“We have taken a measured approach to rate setting, in conditions of high uncertainty, but we remain focused on our price-stability mandate,” Kganyago said.
“It is crucial that inflation reverts to 3% as the current shock fades, and we take responsibility for delivering that outcome.”
Rate Path Shows Cuts Later in Forecast Period
According to the central bank’s Quarterly Projection Model, the policy rate is expected to remain broadly stable through the remainder of 2026, with cuts projected later as inflation falls to 3% and the model moves to a more neutral policy stance.
“As before, this rate path remains a broad policy guide,” Kganyago said. “Our decisions will continue to be taken on a meeting-by-meeting basis, with careful attention to the outlook, data outcomes, and the balance of risks to the forecast.”
Domestic Reforms Remain Best Growth Option
Kganyago concluded by emphasising that domestic reforms are South Africa’s best growth option amid the adverse global environment. This includes structural interventions to improve productivity in transport and energy sectors, as well as the macroeconomic goals of sustainable debt and permanently lower inflation.
“In a world of excessive debt and elevated inflation, our macro fundamentals are becoming a differentiating factor for South Africa, lowering our country risk premium and helping to protect us from the global bond selloff,” he said.
“As the Monetary Policy Committee, our primary role is to protect the value of the currency, by getting inflation back to 3% over time. We will act as needed to achieve this goal.”
Stephan Potgieter, CEO of BetterHome Group Mortgage Origination and BetterBond, says:
Homeowners will face some renewed pressure on their monthly bond repayments as the Reserve Bank has increased the repo rate by 25 basis points.
But there is good news: inflation is easing, and that could pave the way for a rate cut in the future. Inflation fell from 5.0% in June to 4.3% in July – only marginally above the upper end of the inflation target range. The rand has also remained resilient in recent months, helping to contain the cost of imported goods.
Although this isn’t the outcome households were hoping for, the increase should be viewed as a precautionary measure to absorb any potential oil price shocks amid ongoing hostilities in the Middle East.
And while the prime lending rate is now 10.75%, it remains below the levels seen in 2023, when it reached 11.75%. That means homeowners are still paying less on their bonds than they were three years ago. For someone with a R2 million bond, the difference is just over R1 360 less each month.
So, while this latest increase will test some household budgets, the easing of inflation and a resilient rand offer reassurance that interest rates could start coming down again in the future.